2026 Fed Rate Outlook: 0.5% Hike & Your Finances
Advertisers
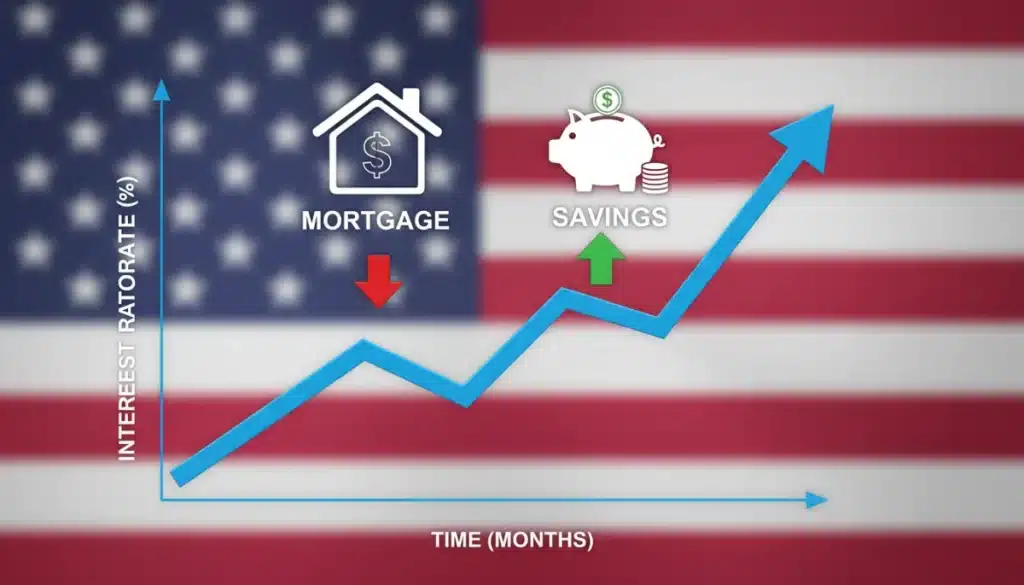
A projected 0.5% Federal Reserve interest rate hike in 2026 is anticipated to directly increase mortgage costs and potentially boost savings account yields for consumers.
As we look towards 2026, the economic landscape is continually evolving, with particular attention focused on the Federal Reserve’s monetary policy. The prospect of a 2026 Fed Rate Hike, specifically a projected 0.5% increase, is a topic of significant discussion among economists, financial analysts, and everyday Americans. This anticipated adjustment carries substantial implications for various aspects of personal finance, from the cost of borrowing for a home to the returns on your hard-earned savings. Understanding these potential shifts is crucial for prudent financial planning in the coming years.
Advertisers
Understanding the Federal Reserve’s Role and Rate Hikes
The Federal Reserve, often referred to as the Fed, serves as the central banking system of the United States. Its primary mandates include maximizing employment, stabilizing prices, and moderating long-term interest rates. To achieve these goals, the Fed utilizes various tools, with changes to the federal funds rate being one of the most impactful. A rate hike, such as the projected 0.5% increase in 2026, directly influences the cost of short-term borrowing for banks, which then cascades through the entire financial system.
Advertisers
When the Fed raises interest rates, it generally aims to cool down an overheating economy, curb inflation, or strengthen the dollar. Conversely, lowering rates is typically done to stimulate economic growth. The decision to adjust rates is not made lightly and involves careful consideration of numerous economic indicators, including inflation data, employment figures, and global economic conditions. The market often anticipates these moves, but the precise timing and magnitude can still cause significant ripples.
The Mechanism of Rate Transmission
- Short-Term Lending: Banks borrow from each other at rates influenced by the federal funds rate.
- Consumer Loans: These changes affect prime rates, which then dictate rates on credit cards, auto loans, and adjustable-rate mortgages.
- Long-Term Debt: While less direct, bond yields and fixed-rate mortgages are also influenced by the Fed’s stance and inflation expectations.
In essence, a 0.5% hike in the federal funds rate signals a tightening of monetary policy, making money more expensive to borrow across the board. This has direct consequences for both borrowers and savers, shaping their financial decisions and overall economic behavior. The Fed’s forward guidance and economic projections play a critical role in how financial markets and consumers prepare for such changes.
Direct Impact on Mortgage Rates and Affordability
One of the most immediate and tangible effects of a 2026 Fed Rate Hike will be on mortgage rates. While the federal funds rate directly influences short-term rates, it indirectly impacts long-term fixed-rate mortgages through its influence on bond yields, particularly the 10-year Treasury yield. A 0.5% increase in the federal funds rate is likely to translate into higher mortgage interest rates, which in turn affects monthly payments and overall housing affordability.
For prospective homebuyers, higher mortgage rates mean a more expensive home loan. A seemingly small increase in the interest rate can add thousands of dollars to the total cost of a mortgage over its lifetime. This could lead to a cooling of the housing market, as some buyers may be priced out or choose to wait for more favorable conditions. Existing homeowners with adjustable-rate mortgages (ARMs) will also feel the pinch, as their interest rates are typically reset periodically based on an index that often moves in tandem with the federal funds rate.
Mortgage Rate Scenarios
- New Homebuyers: Face higher monthly payments and reduced purchasing power.
- ARM Holders: Experience an increase in their variable interest rates, leading to higher payments.
- Refinancing Prospects: May find refinancing less attractive or even detrimental if current rates are lower.
The impact on affordability isn’t just about monthly payments; it also affects the debt-to-income ratios that lenders use to qualify borrowers. Higher rates can make it harder for individuals to meet these criteria, further restricting access to homeownership. Therefore, understanding the potential for a 0.5% hike is vital for anyone planning to enter the housing market or considering refinancing their current mortgage.
Implications for Savings Accounts and Investments
While higher interest rates are generally unwelcome news for borrowers, they often bring a silver lining for savers. A 2026 Fed Rate Hike means that banks can earn more on their reserves held at the Fed, and they typically pass some of these increased earnings onto their customers in the form of higher interest rates on savings accounts, certificates of deposit (CDs), and money market accounts. This can be a significant boost for individuals looking to grow their emergency funds or save for future goals.
For investors, the landscape becomes more complex. Higher interest rates can make fixed-income investments, such as bonds, more attractive compared to stocks, as their yields become more competitive. However, existing bonds may see their market value decrease as new bonds are issued with higher rates. The stock market can also react negatively to rate hikes, as higher borrowing costs can dampen corporate profits and slow economic growth, potentially leading to lower valuations.
Maximizing Savings Returns
- High-Yield Savings Accounts: Seek out online banks or credit unions offering more competitive rates.
- Certificates of Deposit (CDs): Consider locking in higher rates for a fixed period.
- Money Market Accounts: These accounts often offer better rates than traditional savings accounts.
Strategically, savers should consider moving funds from low-yield accounts to those that offer better returns in a rising rate environment. Investors should review their portfolios, potentially rebalancing to account for shifts in bond and stock market attractiveness. The 0.5% hike, while seemingly modest, can create notable opportunities for those who adapt their savings and investment strategies accordingly.
Consumer Spending and Economic Growth Outlook
The ripple effect of a 2026 Fed Rate Hike extends beyond mortgages and savings, influencing broader consumer spending patterns and the overall trajectory of economic growth. When borrowing becomes more expensive, consumers and businesses tend to reduce their spending and investment. This slowdown in demand can help to combat inflation, which is often a primary motivation for the Fed to raise rates.
Higher interest rates on credit cards, personal loans, and auto loans mean that discretionary spending may decrease as households allocate more of their income to debt servicing. Businesses might also postpone expansion plans or reduce hiring if the cost of capital increases significantly. This can lead to a more subdued economic growth environment, which, while potentially necessary to control inflation, can also bring challenges such as slower job creation.
However, the impact is not uniformly negative. A more stable inflationary environment can boost consumer confidence in the long run, and a stronger dollar resulting from higher rates can make imports cheaper. The Fed’s objective is to achieve a ‘soft landing’ – slowing the economy enough to control inflation without triggering a recession. The success of this balancing act will largely determine the broader economic outlook following a 0.5% hike.
Navigating Personal Finance in a Rising Rate Environment
For individuals, proactive financial planning is paramount in anticipation of a 2026 Fed Rate Hike. Understanding how a 0.5% increase could affect your specific financial situation allows for strategic adjustments. This involves reviewing existing debt, optimizing savings, and potentially re-evaluating investment portfolios. The goal is to mitigate potential negatives and capitalize on any opportunities that arise from the changing interest rate landscape.
Those with variable-rate debt, such as credit card balances or adjustable-rate mortgages, should prioritize paying down these obligations before rates climb further. Locking in fixed rates on new loans, if available and advantageous, could also be a wise move. On the savings front, exploring high-yield accounts or short-term CDs can help maximize returns on cash reserves. Diversifying investments to include assets that perform well in different economic conditions is always a sound strategy.
Key Financial Planning Steps
- Debt Management: Prioritize high-interest, variable debt repayment.
- Savings Optimization: Seek out higher-yielding savings vehicles.
- Investment Review: Rebalance portfolios to align with new economic realities.
- Budget Adjustment: Prepare for potentially higher borrowing costs and adjust spending accordingly.
Staying informed about the Fed’s pronouncements and economic data will enable more timely and effective financial decisions. Consulting with a financial advisor can also provide personalized guidance tailored to individual circumstances, helping to navigate the complexities of a rising rate environment with greater confidence.
Historical Context and Future Projections
To fully appreciate the potential impact of a 2026 Fed Rate Hike, it’s helpful to consider historical patterns and the Fed’s past responses to economic conditions. The Federal Reserve has a long history of adjusting interest rates to manage inflation and stimulate growth. Each cycle of rate changes is unique, shaped by the prevailing economic climate, but general principles often apply. Historically, periods of sustained rate hikes have been followed by a moderation of inflation, though sometimes at the cost of slower economic expansion.
Looking ahead to 2026, the projected 0.5% hike is a reflection of the Fed’s current assessment of future economic conditions. These projections are based on a multitude of factors, including anticipated inflation trends, labor market strength, and global economic stability. It’s important to remember that these are projections, not guarantees. Economic forecasts can change rapidly due to unforeseen events, such as geopolitical shifts or new technological advancements.
Analysts and financial institutions constantly update their models and predictions, offering various scenarios for the future of interest rates. While a 0.5% hike is a strong possibility, the actual outcome will depend on how the economy evolves over the next couple of years. Staying abreast of these ongoing discussions and expert analyses will provide a more nuanced understanding of the potential future for interest rates and its implications for personal finances.
| Key Aspect | Impact of 0.5% Fed Rate Hike |
|---|---|
| Mortgage Rates | Likely to increase, raising monthly payments and reducing affordability for new buyers. |
| Savings Accounts | Expected to offer higher interest yields, benefiting savers and CD holders. |
| Consumer Spending | May slow down due to increased borrowing costs for credit cards and loans. |
| Economic Growth | Aims to moderate inflation, potentially leading to slower but more stable growth. |
Frequently Asked Questions About the 2026 Fed Rate Hike
The Federal Reserve typically considers raising interest rates to combat inflation, cool an overheating economy, and maintain price stability. A projected 0.5% hike in 2026 would likely be a response to sustained inflationary pressures or robust economic growth that warrants a tightening of monetary policy to prevent future instability.
If you already have a fixed-rate mortgage, a 0.5% Fed rate hike in 2026 will not directly change your current monthly payments. Your interest rate is locked in. However, for those looking to purchase a new home or refinance, new fixed-rate mortgages will likely be offered at higher interest rates, increasing costs.
While a Fed rate hike generally leads to higher savings account yields, it’s not guaranteed that all banks will immediately pass on the full 0.5% increase. It’s advisable to compare rates from different financial institutions, especially online banks, as they often offer more competitive returns in a rising rate environment.
Credit card interest rates are often tied to the prime rate, which is directly influenced by the federal funds rate. With a 0.5% hike, your credit card interest could increase. Prioritizing the payoff of high-interest credit card debt becomes even more crucial to minimize the financial burden and save money on interest payments.
Federal Reserve projections, while based on extensive economic analysis, are subject to change. They represent the Fed’s best estimate of future economic conditions and policy responses. Unforeseen global events, shifts in inflation, or changes in employment data could lead to adjustments in these projections. It’s important to view them as informed forecasts rather than certainties.
Conclusion
The anticipation of a 2026 Fed Rate Hike of 0.5% casts a significant shadow and light across the financial landscape of the United States. For millions, this projection means re-evaluating financial strategies, from mortgage decisions to savings goals. While higher borrowing costs could present challenges for homebuyers and those with variable-rate debt, the prospect of increased returns on savings accounts offers a welcome opportunity for prudent savers. Ultimately, staying informed, adapting financial plans, and seeking expert advice will be key to navigating these changes successfully and optimizing personal financial well-being in the evolving economic climate.
