Smart 401(k) Allocation for 2026: 10% Higher Growth
Advertisers
Implementing a strategic 401(k) allocation in 2026 can significantly boost growth potential by 10% or more, even when navigating unpredictable market conditions through informed decision-making.
As we navigate the complexities of 2026, understanding how to maximize your retirement savings is more critical than ever. The goal isn’t just to save, but to strategically invest. This article explores how smart 401(k) allocation can help you achieve a 10% higher growth potential in a market that continues to present both challenges and opportunities.
Advertisers
Understanding the 2026 Market Landscape
The financial markets in 2026 are shaped by a confluence of evolving factors, from technological advancements to shifting global economic policies. Investors must acknowledge these dynamics to make informed allocation decisions. Recognizing the landscape is the first step toward optimizing your 401(k) for superior returns.
Geopolitical events and domestic economic policies frequently introduce volatility. Interest rate adjustments by central banks, inflation pressures, and supply chain disruptions can all influence asset performance. Staying updated on these broad trends allows for a more adaptive investment strategy.
Advertisers
Key Economic Indicators to Watch
Monitoring specific economic indicators provides valuable insights into potential market shifts. Gross Domestic Product (GDP) growth, unemployment rates, and consumer confidence indices offer a snapshot of economic health. These indicators often signal broader market directions.
- Inflation rates: High inflation erodes purchasing power and can impact bond yields.
- Interest rate policies: Central bank decisions on rates influence borrowing costs and investment returns.
- Corporate earnings: Strong earnings reports indicate healthy company performance and can drive stock prices.
- Global trade relations: Tariffs and trade agreements affect international markets and specific industries.
Technological innovation, particularly in sectors like artificial intelligence and sustainable energy, continues to drive market growth. Identifying these emerging trends and understanding their potential impact on various industries is crucial. A forward-looking perspective helps in capturing long-term growth opportunities.
In conclusion, the 2026 market landscape demands a proactive and informed approach. Investors who diligently track economic indicators and embrace technological trends are better positioned to make strategic 401(k) allocation decisions, aiming for enhanced growth potential.
Diversification: Your Shield Against Volatility
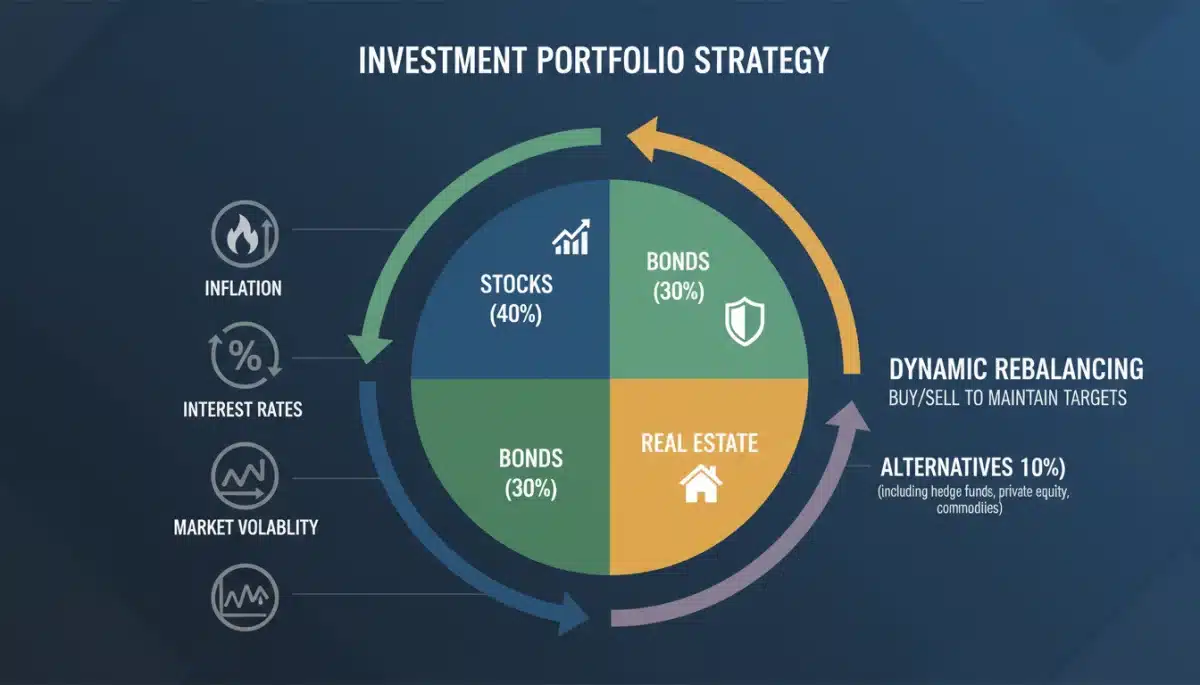
Diversification is a cornerstone of effective investment strategy, especially when aiming for higher growth in a volatile market. It involves spreading your investments across various asset classes, industries, and geographies. This approach helps mitigate risk, ensuring that a downturn in one area doesn’t decimate your entire portfolio.
A well-diversified 401(k) portfolio should include a mix of equities, fixed income, and potentially alternative investments. The specific proportions will depend on your risk tolerance and time horizon. The goal is to create a portfolio that can weather different market conditions.
Beyond Traditional Asset Classes
While stocks and bonds form the core of most 401(k)s, exploring less traditional options can enhance diversification. Real estate investment trusts (REITs) and commodity funds, if available in your plan, can offer additional avenues for growth and stability. These assets often behave differently than stocks and bonds, providing a valuable hedge.
- Global equities: Investing in international markets reduces reliance on a single economy.
- Alternative assets: Consider options like REITs or private equity, if accessible through your 401(k).
- Sector diversification: Avoid over-concentration in a single industry, even a promising one.
- Bond laddering: Staggering bond maturities can help manage interest rate risk.
The principle of not putting all your eggs in one basket remains timeless. Market volatility underscores the importance of this strategy. When one sector or asset class experiences a decline, others might be performing well, offsetting potential losses. This balance is key to maintaining steady growth.
Ultimately, robust diversification is not about eliminating risk entirely but managing it effectively. By spreading investments across a broad spectrum, you increase the likelihood of achieving consistent growth, even when market conditions are unpredictable.
Strategic Rebalancing for Optimal Performance
Strategic rebalancing is a critical component of maintaining an optimal 401(k) allocation. It involves periodically adjusting your portfolio back to its target asset allocation. Over time, market fluctuations can cause certain asset classes to grow faster than others, leading to an unintended shift in your risk profile.
For instance, if stocks have performed exceptionally well, they might come to represent a larger portion of your portfolio than initially planned. Rebalancing would then involve selling some of the outperforming assets and buying underperforming ones. This disciplined approach ensures you don’t take on more risk than you’re comfortable with and helps you buy low and sell high.
When and How to Rebalance
There are two primary approaches to rebalancing: time-based and threshold-based. Time-based rebalancing involves adjusting your portfolio at regular intervals, such as annually or semi-annually. This method offers simplicity and consistency.
- Annual review: A common practice to reassess and rebalance your portfolio.
- Quarterly checks: More frequent reviews can be beneficial in highly volatile markets.
- Threshold rebalancing: Adjust when an asset class deviates by a certain percentage (e.g., 5% or 10%) from its target.
- Automated rebalancing: Some 401(k) plans offer automated rebalancing features, simplifying the process.
Threshold-based rebalancing, on the other hand, is triggered when an asset class deviates by a predetermined percentage from its target allocation. This approach can be more active, responding directly to market movements. Regardless of the method chosen, consistency is paramount.
Rebalancing forces you to take profits from overperforming assets and reinvest in those that may be temporarily undervalued. This counter-cyclical action can significantly enhance long-term returns. It ensures your portfolio aligns with your long-term financial goals and risk tolerance.
In essence, strategic rebalancing is an active management technique that keeps your 401(k) on track. By regularly adjusting your asset mix, you can capitalize on market movements and maintain a balanced, growth-oriented portfolio.
Leveraging Growth Sectors in 2026
Identifying and strategically investing in growth sectors is a powerful way to achieve a 10% higher growth potential in your 401(k) for 2026. Certain industries are poised for significant expansion due to technological breakthroughs, demographic shifts, or evolving consumer preferences. Aligning your investments with these trends can provide a substantial boost.
For 2026, sectors like artificial intelligence (AI), renewable energy, biotechnology, and cybersecurity are expected to continue their robust growth trajectories. These industries are driven by innovation and have strong long-term fundamentals. While they may carry higher risk, their growth potential can significantly outperform traditional sectors.
Emerging Technologies and Sustainable Investments
The proliferation of AI across various industries is creating new efficiencies and products. Investing in companies at the forefront of AI development can yield substantial returns. Similarly, the global push towards sustainability makes renewable energy a compelling growth area, driven by both policy and consumer demand.
- Artificial intelligence: Focus on companies developing AI applications and infrastructure.
- Renewable energy: Invest in solar, wind, and battery storage technologies.
- Biotechnology: Look for innovations in gene therapy, personalized medicine, and drug discovery.
- Cybersecurity: The increasing reliance on digital infrastructure makes this sector essential.
Biotechnology, with its continuous breakthroughs in healthcare, offers another promising avenue. Advances in gene editing and personalized medicine are transforming patient care and creating new market opportunities. Cybersecurity, in an increasingly digital world, is a non-negotiable expense for businesses, ensuring steady demand.
While these sectors offer high growth potential, it’s crucial to maintain diversification within them. Avoid putting all your capital into a single stock, even if it seems promising. Utilize mutual funds or ETFs that focus on these growth sectors to spread risk while capturing upside.
In summary, strategically allocating a portion of your 401(k) to high-growth sectors can significantly enhance your overall returns. By staying informed about emerging trends and maintaining a diversified approach within these sectors, you can position your portfolio for superior performance.
Risk Management in a Volatile Environment
Effective risk management is paramount for achieving consistent growth in your 401(k), especially in volatile markets. Volatility can be unsettling, but with proper strategies, it can also present opportunities. The key is to understand your risk tolerance and implement measures that protect your capital while still allowing for growth.
One fundamental aspect of risk management is understanding the difference between market risk and idiosyncratic risk. Market risk affects all investments and cannot be diversified away. Idiosyncratic risk, specific to an individual asset or company, can be mitigated through diversification. Your focus should be on managing both.
Implementing Protective Strategies
Several strategies can help manage risk within your 401(k). Asset allocation, as previously discussed, is a primary tool. Adjusting the proportion of stocks to bonds based on your age and risk appetite is crucial. Younger investors typically have a higher capacity for risk, while those closer to retirement might prefer more conservative allocations.
- Dollar-cost averaging: Invest a fixed amount regularly, regardless of market fluctuations.
- Stop-loss orders: Though less common in 401(k)s, understanding their principle can guide decisions.
- Emergency fund: Having sufficient liquid savings prevents needing to withdraw from your 401(k) during market downturns.
- Regular portfolio reviews: Monitor your investments to ensure they still align with your goals and risk profile.
Consider the role of cash or cash equivalents within your portfolio. While not a growth asset, holding a small percentage in cash can provide liquidity during market downturns, allowing you to buy assets at lower prices. This tactical allocation can be a powerful risk management tool.
Furthermore, avoiding emotional decision-making during volatile periods is vital. Panicked selling can lock in losses and prevent you from participating in subsequent recoveries. A disciplined, long-term perspective is often the best defense against market swings.
To conclude, effective risk management is about balancing protection with growth potential. By understanding your risk tolerance, diversifying wisely, and adhering to a disciplined investment strategy, you can navigate volatile markets and safeguard your 401(k) for future prosperity.
The Role of Personalized Financial Guidance
Navigating the complexities of 401(k) allocation in 2026, especially with the goal of achieving 10% higher growth, can be significantly enhanced by personalized financial guidance. While self-directed investing is an option, a professional advisor can offer tailored strategies and insights that align with your unique financial situation and goals.
A financial advisor can help you assess your current financial standing, determine your true risk tolerance, and project potential retirement outcomes. They can also provide an objective perspective, helping you avoid emotional pitfalls that often derail even the best-laid investment plans during volatile periods.
Benefits of Professional Advice
Beyond basic asset allocation, advisors can assist with more nuanced aspects of your 401(k). This includes understanding the specific investment options available within your plan, optimizing tax efficiency, and integrating your 401(k) strategy with other financial goals, such as college savings or real estate investments.
- Customized asset allocation: Tailoring your portfolio to your specific circumstances.
- Tax optimization: Strategies to minimize taxes on your 401(k) contributions and withdrawals.
- Retirement planning: Integrating your 401(k) into a comprehensive retirement strategy.
- Behavioral coaching: Helping you stay disciplined during market fluctuations.
Choosing the right financial advisor is crucial. Look for certified professionals (e.g., Certified Financial Planner™ or CFP®) who operate as fiduciaries, meaning they are legally bound to act in your best interest. Interview several advisors to find one whose philosophy and communication style resonate with you.
Even if you prefer a more hands-on approach, a periodic consultation with a financial professional can provide valuable checkpoints. They can review your portfolio, offer suggestions for adjustments, and ensure you remain on track toward your growth objectives. This external validation can be incredibly reassuring.
In essence, personalized financial guidance can act as a catalyst for achieving superior 401(k) growth. By leveraging expert advice, you can make more informed decisions, mitigate risks, and confidently pursue your retirement savings goals.
Future-Proofing Your 401(k) for Long-Term Success
Future-proofing your 401(k) goes beyond immediate allocation decisions; it involves creating a resilient investment strategy that can adapt to unforeseen changes. The market of 2026, and beyond, will undoubtedly present new challenges and opportunities. A forward-thinking approach ensures your retirement savings remain robust and continue to grow.
One key aspect of future-proofing is maintaining a long-term perspective. While short-term market fluctuations can be concerning, focusing on your ultimate retirement goals helps to weather these storms. Remember, a 401(k) is a long-haul investment vehicle, designed to grow over decades.
Adapting to Demographic and Technological Shifts
Demographic trends, such as an aging population, can influence market dynamics, particularly in healthcare and consumer goods. Similarly, rapid technological advancements can create new industries and disrupt old ones. Your 401(k) allocation should be flexible enough to respond to these large-scale shifts.
- Regular strategy reviews: Annually assess if your strategy still aligns with market realities.
- Embrace innovation: Be open to new investment opportunities arising from technological advancements.
- Stay informed: Continuously educate yourself on economic trends and investment principles.
- Flexibility: Be prepared to adjust your plan as life circumstances and market conditions evolve.
Consider the impact of inflation on your future purchasing power. While not always a direct allocation decision, understanding how inflation erodes returns can guide your choice of inflation-hedging assets, such as Treasury Inflation-Protected Securities (TIPS) or real estate, if available in your plan.
Finally, regularly reviewing your beneficiary designations and ensuring your estate plan is up-to-date is part of future-proofing. These administrative details often get overlooked but are crucial for ensuring your assets are distributed according to your wishes. A comprehensive approach covers both investment strategy and essential planning.
To conclude, future-proofing your 401(k) means building a flexible, informed, and resilient investment strategy. By anticipating changes and maintaining a long-term outlook, you can ensure your retirement savings are well-positioned for sustained success, regardless of what the future holds.
| Key Point | Brief Description |
|---|---|
| Market Awareness | Monitor 2026 economic indicators and technological trends for informed decisions. |
| Diversification | Spread investments across various asset classes to mitigate risk and ensure stability. |
| Strategic Rebalancing | Periodically adjust portfolio to target allocations, capitalizing on market movements. |
| Growth Sectors | Allocate to high-potential industries like AI and renewable energy for enhanced returns. |
Frequently Asked Questions About 401(k) Allocation
A smart 401(k) allocation for 2026 involves diversifying across asset classes, strategically rebalancing, and considering high-growth sectors like AI and renewable energy. It also means aligning your investments with your risk tolerance and long-term financial goals, adapting to market conditions.
Achieving 10% higher growth potential often requires a proactive approach. This includes optimizing your asset allocation, regularly rebalancing your portfolio, and selectively investing in emerging growth sectors. Minimizing fees and seeking personalized financial guidance can also significantly contribute to enhanced returns.
Market volatility can be both. While it can cause short-term declines, it also presents opportunities to buy assets at lower prices through dollar-cost averaging and strategic rebalancing. For long-term investors, volatility can be leveraged to enhance returns, provided a disciplined approach is maintained.
Using a financial advisor can be highly beneficial. They offer personalized advice, help with tax optimization, and provide objective insights to navigate complex market conditions. A good advisor ensures your 401(k) strategy aligns with your broader financial goals, especially in volatile markets.
For 2026, key growth sectors include artificial intelligence, renewable energy, biotechnology, and cybersecurity. These industries are driven by ongoing innovation and strong demand, offering significant potential for investment growth. Diversifying within these sectors is recommended to mitigate specific company risks.
Conclusion
Optimizing your 401(k) allocation for 2026 is a dynamic process that demands ongoing attention and informed decision-making. By embracing diversification, implementing strategic rebalancing, identifying promising growth sectors, and effectively managing risk, you can significantly enhance your retirement savings. The pursuit of a 10% higher growth potential is an achievable goal for those who remain disciplined and adaptable in their investment approach. Remember that personalized financial guidance can provide invaluable support in navigating the evolving market landscape, ensuring your long-term financial success. Your retirement future depends on the choices you make today.
